Treasury Inflation-Protected Securities, or TIPS, are U.S. government bonds designed to adjust their principal for changes in consumer prices. They can help protect purchasing power, but their market value and after-tax return can still fluctuate.
How Treasury Inflation-Protected Securities Work
The U.S. Treasury sells TIPS with original maturities of 5, 10 and 30 years, and investors can hold or trade them after issuance. TreasuryDirect explains that the security’s principal may move up or down during its term as inflation or deflation changes the reference index.
The coupon rate does not change after auction, but the cash interest payment changes because Treasury multiplies that fixed rate by the adjusted principal. At maturity, Treasury pays the inflation-adjusted principal or the original principal, whichever is greater, although an investor who sells earlier receives the market price instead.
Individual investors can buy newly issued TIPS through TreasuryDirect or eligible financial institutions, while previously issued securities trade in the secondary market. Auction price and real yield determine whether a buyer pays at, above or below par.
Secondary-market buyers should verify the accrued inflation adjustment and accrued interest included in the settlement amount. Those details affect the cash paid even when two securities share the same coupon and maturity date.
How Inflation Changes TIPS Payments
Treasury links the principal adjustment to the non-seasonally adjusted Consumer Price Index for All Urban Consumers, or CPI-U. The Bureau of Labor Statistics defines CPI as the average change over time in prices paid by urban consumers for a market basket of goods and services.
Inflation can increase both the adjusted principal and the dollar value of future interest payments, while deflation can reduce them before maturity. This design differs from a conventional Treasury note or bond, where principal stays fixed and inflation can erode the purchasing power of future payments.
The daily index ratio published by Treasury translates the reference CPI changes into an adjusted principal amount for each security. Because CPI data arrive with a lag, the adjustment does not track a household’s expenses in real time.
Investors often compare a TIPS real yield with the nominal yield on a conventional Treasury of similar maturity. The difference is commonly called the breakeven inflation rate, although liquidity and risk premiums mean it is not a pure forecast of future inflation.
What Investors Should Check Before Buying TIPS
TIPS prices can fall when real interest rates rise, so inflation protection does not guarantee a gain if an investor sells before maturity. Investors should compare the real yield, remaining maturity, bid-ask spread and tax treatment rather than focusing only on the coupon rate.
A TIPS mutual fund or exchange-traded fund does not have one maturity date that guarantees the return of an investor’s original purchase amount. Fund shareholders remain exposed to portfolio turnover, fees and market-price changes even when the underlying securities carry the full faith and credit of the U.S. government.
Federal tax rules can also create taxable income from an inflation-driven principal increase before the investor receives that amount in cash at maturity. TreasuryDirect’s tax guidance notes that TIPS investors may receive Form 1099-OID for changes in inflation-adjusted principal, while Treasury interest is generally exempt from state and local income taxes.
TIPS can complement an investor’s review of the Consumer Price Index, the relationship between bond prices and yields and the cash flow statement used to assess corporate issuers. They are not a complete inflation hedge for every spending pattern because each household’s costs can differ from the CPI basket.
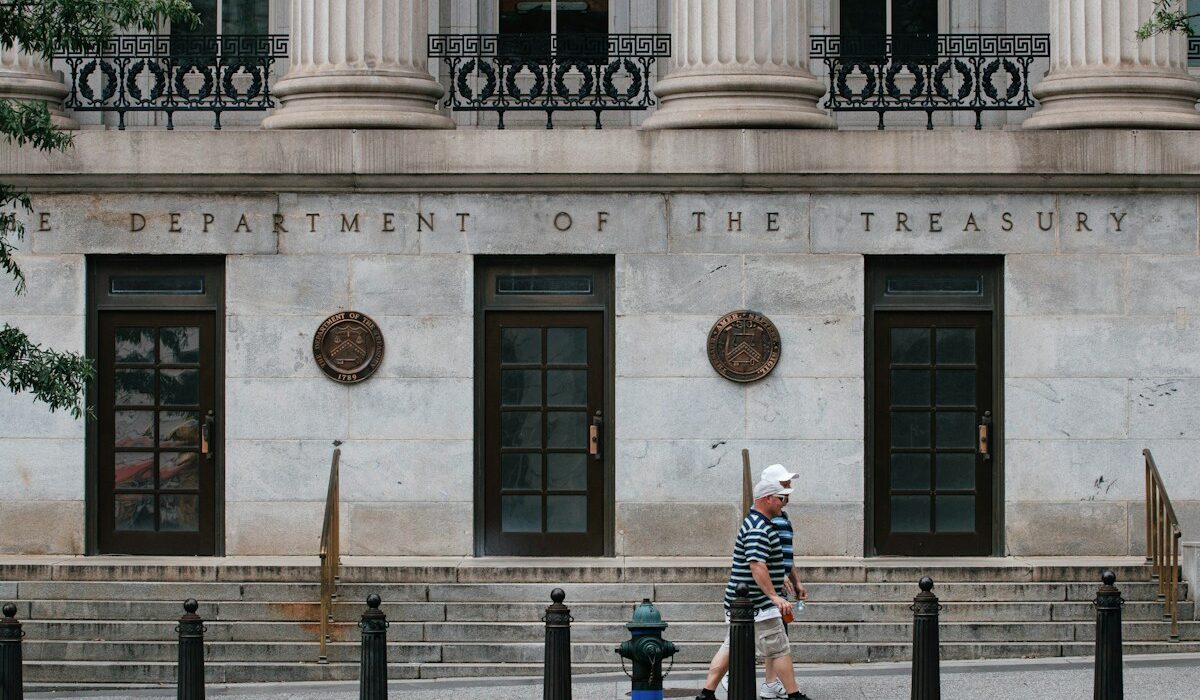
Featured image: U.S. Department of the Treasury by Connor Gan via Unsplash. The photograph shows the Treasury building associated with the issuer of TIPS.

Sharron Kendi
Sharron Kendi is a seasoned crypto market analyst and writer with over three years of experience decoding blockchain trends, price movements, and market dynamics. She holds a Bachelor’s Degree in Commerce (Finance) from Kenyatta University, blending a solid academic foundation with a sharp eye for technical analysis and a deep understanding of on-chain data. Her work delivers clear, data-driven insights that empower investors to navigate the fast-evolving digital asset space with confidence.