Preferred stock is an ownership security that usually sits between common shares and corporate bonds in a company’s capital structure. It can provide a stated dividend and a stronger claim than common stock, but its legal terms vary by issue and require close reading.
For investors, the central trade-off is income and priority in exchange for limited voting power and less participation in a company’s growth. The security can also react sharply to interest-rate changes, credit risk and issuer call decisions.
How Preferred Stock Fits in the Capital Structure
The U.S. Securities and Exchange Commission’s Investor.gov stock guide explains that preferred shareholders typically receive dividends before common shareholders. If a company enters bankruptcy and liquidates, preferred holders also stand ahead of common shareholders, although bondholders and other creditors retain higher priority.
That position does not make preferred stock the same as debt. Preferred holders are owners, and the issuer’s board usually has discretion over dividend declarations unless the governing documents create specific obligations or remedies. Investors should therefore examine the prospectus rather than treating a stated dividend rate as guaranteed income.
Preferred shares also commonly lack the voting rights attached to common shares. Investor.gov’s preferred stock definition highlights the trade-off: dividend preference and liquidation priority often come with reduced influence over corporate elections.
Terms That Change the Income Profile
A cumulative preferred issue records missed dividends and generally requires the company to pay those arrears before resuming common-stock dividends. A noncumulative issue normally does not preserve skipped payments, making dividend interruptions more consequential for income-focused holders.
Fixed-rate preferred shares can lose market value when prevailing yields rise because new securities may offer more attractive income. Floating-rate or reset-rate issues may reduce some rate sensitivity, but investors still face issuer credit risk, thin trading and the possibility that reset formulas produce lower-than-expected payments.
Many preferred shares are callable, meaning the issuer can redeem them after a stated date and at a stated price. A company may exercise that option when refinancing becomes cheaper, so investors should compare the current price with the call price and calculate yield-to-call instead of relying only on the headline dividend rate.
How Investors Compare Preferred and Common Shares
Common shares typically offer greater upside when earnings grow, while preferred shares emphasize contractual terms and cash distributions. Investors can compare those claims with the basics in our earnings per share guide and use our P/E ratio explainer to understand how the market values common equity.
Credit quality matters because a preferred dividend depends on the issuer’s capacity to generate cash and maintain access to capital. Our debt-to-equity ratio guide shows how leverage can amplify financial risk, while the preferred prospectus identifies subordination, call and dividend rules for the specific security.
Investors should also review liquidity, tax treatment and concentration before buying. Exchange-listed preferred shares may trade less actively than large common stocks, which can widen bid-ask spreads and increase execution costs during volatile sessions.
A diversified position can reduce exposure to a single issuer or sector, but it cannot eliminate broad rate or credit risk. A high stated yield may compensate for real exposure to rates, credit deterioration or an unfavorable call, so the full terms matter more than the label “preferred.”
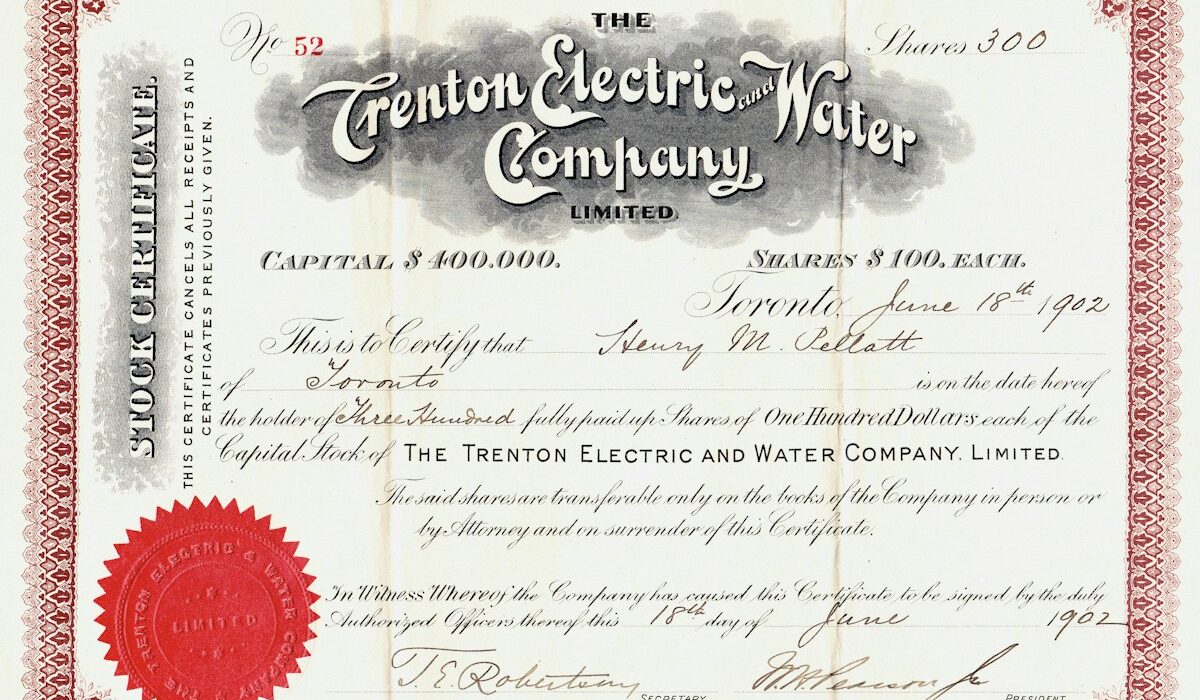
Featured image: historic share certificate photographed by Community Archives of Belleville and Hastings County via Unsplash.

Sharron Kendi
Sharron Kendi is a seasoned crypto market analyst and writer with over three years of experience decoding blockchain trends, price movements, and market dynamics. She holds a Bachelor’s Degree in Commerce (Finance) from Kenyatta University, blending a solid academic foundation with a sharp eye for technical analysis and a deep understanding of on-chain data. Her work delivers clear, data-driven insights that empower investors to navigate the fast-evolving digital asset space with confidence.