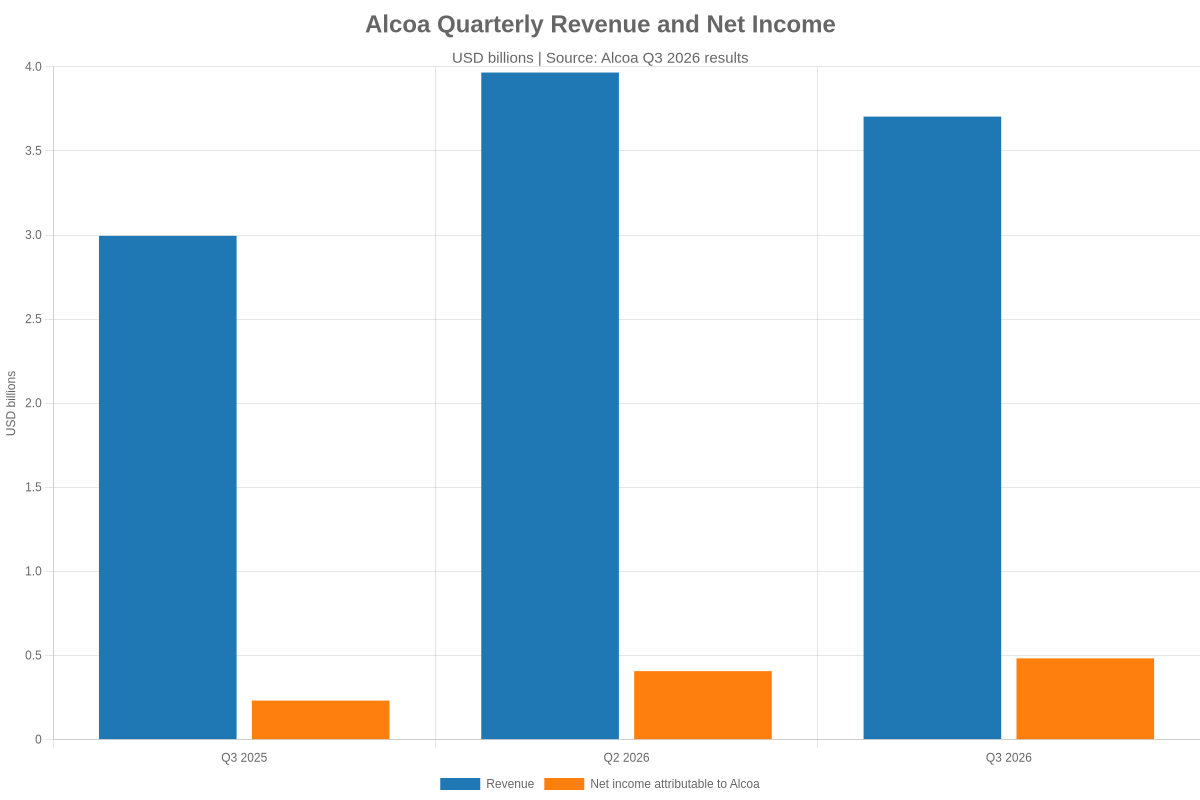
Alcoa reported stronger year-over-year profit and higher production in the third quarter, even as revenue eased from the previous three months. The aluminum producer said on October 15 that net income attributable to Alcoa reached $483 million, or $1.81 per share, for the quarter ended September 30.
Revenue was $3.70 billion, down 7% from the second quarter but up from $3.00 billion a year earlier. The results give investors a mixed picture: operating output improved and profit expanded, while weaker aluminum segment revenue weighed on the sequential comparison.
Profit Improves as Revenue Moderates
Adjusted EBITDA excluding special items was $789 million, compared with $901 million in the second quarter and $270 million in the year-earlier period. Adjusted earnings per share fell sequentially to $1.82 from $2.12, but improved sharply from a two-cent adjusted loss a year ago. Those figures separate the underlying operating trend from acquisition financing and other special items.
Alcoa generated $643 million of cash from operations and $472 million of free cash flow. It ended the quarter with $4.4 billion of cash, including $2.6 billion of financing proceeds earmarked for the pending acquisition of Australia’s Aluminium Limited, or AliGroup. Investors comparing industrial earnings can also review PNC’s latest quarterly results.
Higher Alumina and Aluminum Output
Alumina segment revenue rose 7% sequentially, helped by higher shipments and production, while aluminum segment revenue declined 9%. The production gains matter because higher volumes can spread fixed costs across more output, although realized commodity prices and raw-material costs remain central to margins.
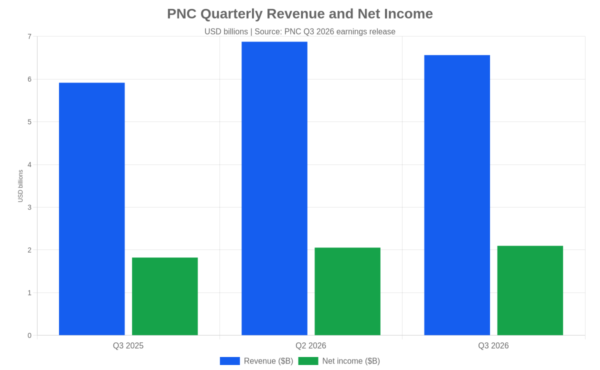
The chart below uses Alcoa’s reported quarterly figures and shows that attributable net income continued to rise even as third-quarter revenue slipped from the second-quarter level. It is an original visualization of the company’s figures, not an estimate. For another materials-sensitive earnings read, see TSMC’s third-quarter update.
Outlook and AliGroup Deal
Alcoa maintained its 2026 outlook for alumina production of 9.5 million to 9.6 million metric tons and alumina shipments of 11.5 million to 11.6 million metric tons. It also continues to expect aluminum production of 2.4 million to 2.6 million metric tons and shipments of 2.6 million to 2.8 million metric tons.
For the fourth quarter, management expects an approximately $30 million adverse effect from higher raw-material prices and maintenance in the aluminum segment, plus another roughly $30 million adverse effect from higher alumina costs. South32 shareholders approved the AliGroup transaction on October 15, and Alcoa continues to target completion in the first half of 2027. Broader portfolio positioning is covered in BlackRock’s quarterly ETF-flow results.
Source: Alcoa Corporation Q3 2026 results, published October 15, 2026.

Elsy kanana
Elsy Kanana is a financial and cryptocurrency journalist at FusionMarketNews, covering digital assets, blockchain technology, financial markets, and emerging fintech trends. Her reporting focuses on market movements, regulatory developments, and on-chain analytics, delivering clear, data-driven insights to readers worldwide.