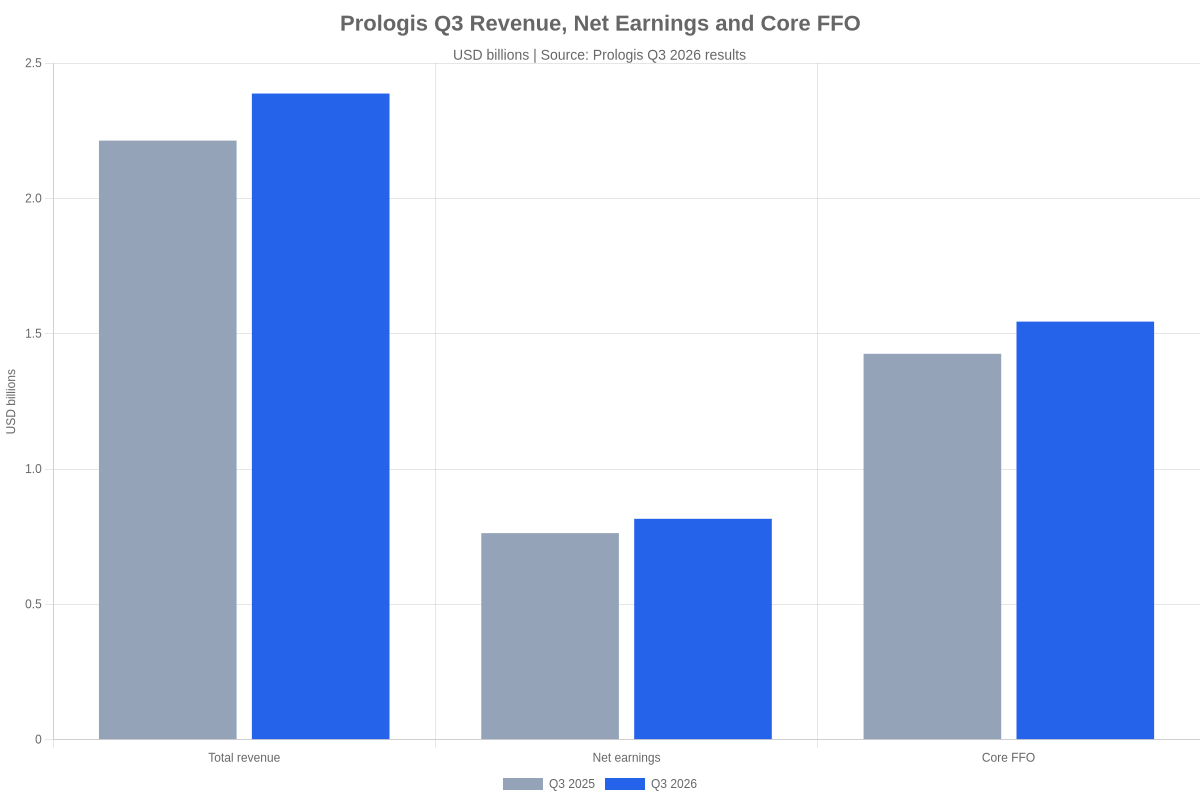
Prologis Q3 earnings improved as the logistics-property company recorded higher revenue, net earnings and Core funds from operations. Prologis said on October 15 that total revenue reached $2.39 billion for the quarter ended September 30, up from $2.21 billion a year earlier.
Net earnings attributable to common stockholders rose to $816 million from $763 million. Core FFO, a non-GAAP measure commonly used for real estate investment trusts, increased to $1.55 billion from $1.43 billion.
Prologis Q3 Earnings and Revenue Rise
Net earnings per diluted share increased to $0.86 from $0.82 in the third quarter of 2025. Core FFO per diluted share rose to $1.60 from $1.49, while Core FFO excluding net promote income or expense reached $1.61 from $1.50.
Rental and other revenue increased to $2.22 billion from $2.06 billion. Strategic-capital revenue rose to $164 million from $150 million. Investors comparing the results with other quarterly reports can review Alcoa’s third-quarter earnings.
Prologis Q3 Earnings Reflect High Occupancy
Average occupancy was 95.1%, while period-end occupancy reached 95.6%. Cash same-store net operating income grew 5.9%, and net effective rent change was 38%. Prologis said it commenced leases covering 55.9 million square feet during the quarter.
The company reported $702 million of acquisitions and $964 million of development starts. It also stabilized $401 million of developments at an estimated weighted-average yield of 5.6%. Available liquidity stood at approximately $8.8 billion at quarter-end.
Guidance Shifts Toward More Deployment
Prologis narrowed 2026 Core FFO guidance to $6.25–$6.29 per share from $6.22–$6.30. It lowered net earnings guidance to $4.05–$4.15 per share from $4.40–$4.55, partly reflecting items treated differently between GAAP earnings and Core FFO.
The company raised its development-start range to $5.0 billion–$5.75 billion and its acquisition range to $2.1 billion–$2.3 billion. Management linked demand to e-commerce, advanced manufacturing and the data-center supply chain, while noting the pending SEGRO combination. Broader supply-chain risks are examined in the BIS chokepoint analysis.
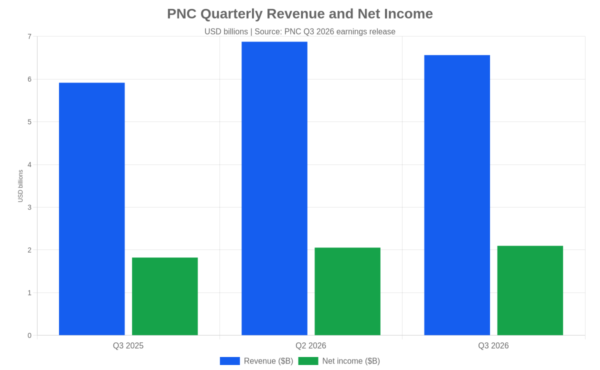
Prologis ended the quarter with debt equal to 4.5 times adjusted EBITDA and a 3.3% weighted-average interest rate on its share of total debt. Financing conditions therefore remain relevant alongside operating growth. Bank-sector comparisons are available in PNC’s quarterly loan and earnings report.
Source: Prologis third-quarter 2026 results, released October 15, 2026.

Sharron Kendi
Sharron Kendi is a seasoned crypto market analyst and writer with over three years of experience decoding blockchain trends, price movements, and market dynamics. She holds a Bachelor’s Degree in Commerce (Finance) from Kenyatta University, blending a solid academic foundation with a sharp eye for technical analysis and a deep understanding of on-chain data. Her work delivers clear, data-driven insights that empower investors to navigate the fast-evolving digital asset space with confidence.